Oil and gas automation is becoming a strategic requirement, not merely an equipment upgrade. Producers now manage aging assets, tighter margins, cybersecurity risks, and pressure to reduce emissions. The International Energy Agency’s World Energy Outlook 2024 highlights continuing uncertainty across energy markets, making operational resilience increasingly valuable. Automation supports that resilience through real-time monitoring, predictive maintenance, digital twins, and safer remote control.
Market estimates vary. MarketsandMarkets projects the global oil and gas automation market to grow from approximately USD 20 billion in the late 2020s, supported by digital transformation and industrial connectivity. Grand View Research also identifies process automation, supervisory control, and data acquisition systems as major growth areas. These figures are useful, but they should not be treated as exact measurements. Research methods differ.
This guide examines ten leading suppliers serving upstream, midstream, refining, and petrochemical operations. The comparison considers control systems, instrumentation, industrial software, cybersecurity, lifecycle support, and integration capability. Companies such as ABB, Emerson, Honeywell, Schneider Electric, Siemens, and Yokogawa remain influential because their platforms connect field sensors with centralized decision-making.
The practical test is simple. Can an operator detect a pressure change before production suffers? Can engineers reduce unnecessary shutdowns without weakening safety controls? Reports from ARC Advisory Group and Deloitte emphasize that successful automation depends on workforce skills, data quality, and implementation discipline. Technology alone is not enough.
Some rankings remain debatable. Regional expertise can matter more than global revenue. A smaller specialist may outperform a larger supplier in a difficult brownfield project. This overview therefore values measurable capability, documented experience, and credible support over marketing language.
Oil and gas automation suppliers provide technologies that measure, control, and optimize industrial operations. Their scope includes sensors, distributed control systems, safety instruments, industrial networks, analytics, and cybersecurity services. Upstream applications monitor wells, pumps, pressure, and production conditions. Midstream systems manage pipelines, storage terminals, leak detection, and compressor stations. Downstream facilities use automation for refining, blending, loading, and emissions control. The boundary is not perfectly clean. A supplier may deliver equipment, software, integration, training, and long-term maintenance together. This overlap sometimes creates confusing market classifications.
Grand View Research’s 2024 market analysis estimated the global oil and gas automation market at over USD 20 billion in 2023. It also projected continued growth through 2030, driven by remote operations, aging assets, and stricter efficiency requirements. The International Energy Agency’s Global Methane Tracker 2024 reports that nearly 75% of fossil-fuel methane emissions could be reduced with existing measures. Around 40% could be avoided at no net cost, according to the report. Automation suppliers support this effort through continuous monitoring, automated shutdowns, and digitally verified maintenance records. Yet technology alone is insufficient. Poor sensor placement, weak data governance, or outdated worker training can undermine results. That is the uncomfortable part. Reliable suppliers must prove performance in harsh, hazardous environments, not only in demonstrations.
Oil and gas automation suppliers support the complete hydrocarbon value chain through control systems, safety systems, instrumentation, industrial software, asset monitoring, and remote operations. This scope chart maps the conventional operational areas covered by automation solutions across upstream, midstream, and downstream activities. The figures represent the number of major process areas included in each segment, rather than supplier revenue or company market share.
Ranking leading oil and gas automation suppliers requires more than counting product lines. We assess field experience across upstream, midstream, and downstream operations. Evidence matters: commissioning records, outage logs, maintenance results, and operator feedback. A supplier with ten years of stable service may deserve more weight than one with impressive but untested features. Site visits, when possible, reveal practical details, such as cabinet labeling, spare-part storage, and alarm response times. These observations often challenge polished presentations.
Technical capability receives a clear score. We examine control-system compatibility, process safety functions, industrial cybersecurity, data integration, and support for brownfield upgrades. Engineering teams should explain failure modes in plain language. They should also provide training records and documented change-control procedures. Independent certifications and audited quality systems strengthen authority, but certificates alone cannot prove performance. We compare references from facilities with similar scale, hazards, and regulatory requirements. That comparison reduces marketing bias.
Reliability includes response time, spare-parts availability, lifecycle planning, and financial resilience. We score service coverage by actual technician access, not regional promises. Commercial transparency matters too. Hidden integration costs can distort a ranking. Our weighting may favor safety and uptime over initial price, although this choice deserves review for smaller operators. No ranking is flawless. Data can be incomplete, and customer references may be selective. We therefore record confidence levels beside each score, revisit results annually, and separate verified evidence from informed judgment.
The top ten global oil and gas automation suppliers are best compared by capability, not publicity.
This profile set examines process control, safety systems, field instrumentation, industrial software, robotics, electrification, and cybersecurity. Leading suppliers typically support offshore platforms, refineries, compressor stations, and aging brownfield assets. Their strongest advantage is often integration.
A reliable control room should connect pressure transmitters, emergency shutdown systems, historian servers, and maintenance alerts without creating alarm floods.
The IEA’s Oil 2024 report projects global oil demand to increase by 3.2 million barrels per day between 2023 and 2030.
That growth raises pressure for safer and more efficient operations. The ten supplier profiles therefore assess uptime, digital compatibility, functional safety expertise, lifecycle support, and regional engineering capacity. Grand View Research also forecasts continued expansion in the oil and gas automation market through 2030, driven by remote monitoring and production optimization.
The exact market value differs across reports. That difference deserves caution.
Some suppliers specialize in high-integrity safety systems. Others focus on predictive maintenance, autonomous inspection, or low-carbon process control. The strongest profiles combine field experience with measurable results, such as fewer unplanned shutdowns, faster turnaround inspections, and lower energy use per barrel.
Cybersecurity must be visible too, especially for remote assets and connected control networks.
The World Economic Forum’s Future of Jobs Report 2023 warns that 44% of workers’ skills may be disrupted within five years.
Training is therefore part of supplier quality. The ranking remains imperfect. A technically advanced platform can still fail when operators receive weak support, unclear documentation, or poor local service.
Oil and gas automation suppliers now compete through integrated technologies, not isolated instruments. Their core offerings include distributed control systems, safety instrumented systems, industrial IoT platforms, and digital twins. These tools connect pressure sensors, pumps, valves, and control rooms across harsh production sites. The International Energy Agency reported that upstream oil and gas investment could reach about $570 billion in 2024. That scale increases demand for reliable automation, remote monitoring, and energy-efficient operations.
Leading suppliers also provide predictive maintenance, machine learning, robotics, and secure edge computing. Predictive models can identify abnormal vibration before a compressor fails. Digital twins can test production changes without interrupting live equipment. McKinsey research indicates that predictive maintenance may reduce machine downtime by 30% to 50%. Cybersecurity is equally important. The International Energy Agency has repeatedly highlighted digitalisation as both an efficiency opportunity and a new security risk. Secure-by-design software, network segmentation, and continuous access control are therefore essential.
Yet no platform is perfect. Legacy equipment often lacks clean data, and poor sensor calibration can mislead even advanced algorithms. The World Economic Forum’s Future of Jobs Report 2023 found that 44% of workers’ core skills may change by 2027. Suppliers must support practical training, clear interfaces, and human review. Automation should assist operators, not quietly replace their judgment. That lesson remains easy to ignore.
Top 10 Oil and Gas Automation Suppliers Worldwide
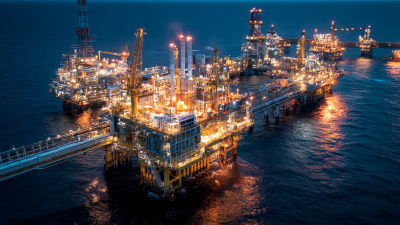
Automation suppliers support drilling, processing, storage, and pipeline operations across the energy sector. Their systems connect sensors, control units, safety functions, and production data. In processing plants, automated valves regulate pressure and temperature around the clock. Offshore platforms use remote monitoring to reduce inspection risks and improve response times. Pipeline operators rely on leak detection, flow measurement, and predictive maintenance tools.
Regional needs differ sharply. North American facilities often prioritize brownfield upgrades and cybersecurity. Middle Eastern operators commonly demand high-temperature equipment and long-term field support. European projects focus more heavily on emissions monitoring, electrification, and energy efficiency. Asian markets need scalable systems for expanding refineries and complex manufacturing networks. Local engineering teams remain essential. Imported technology alone rarely solves site-specific problems.
Emerging trends include edge computing, digital twins, wireless sensors, and artificial intelligence for equipment diagnostics. These tools can identify abnormal vibration before a pump fails. Yet data quality remains a stubborn weakness. Old instruments may produce gaps, false alarms, or inconsistent readings. Some automation pilots also stall because workers receive limited training. That is an uncomfortable lesson. Reliable suppliers now combine technical integration, documented testing, secure software updates, and responsive regional service. Human judgment still matters, especially during unusual operating conditions.
An anonymized industry comparison based on commonly reported automation capabilities, oil and gas use cases, geographic coverage, standards support, and technology trends.
| Rank | Supplier Profile | Core Automation Portfolio | Primary Oil and Gas Applications | Typical Regional Reach | Key Standards and Protocols | Emerging Technology Focus | Typical Project Strength |
|---|---|---|---|---|---|---|---|
| 1 | Global Process Control Platform Provider | Distributed control systems, safety instrumented systems, supervisory control, industrial networking, and asset-management software. | Refineries, gas-processing plants, LNG facilities, petrochemical units, and large onshore production assets. | North America, Europe, the Middle East, Asia-Pacific, and major energy markets in Latin America. | IEC 61508 IEC 61511 OPC UA Ethernet/IP | Cloud-connected operations, digital twins, advanced process control, predictive maintenance, and cybersecurity monitoring. | Large greenfield projects, complex brownfield modernization, and multi-site standardization. |
| 2 | Industrial Electrification and Control Integrator | Motor-control systems, variable-frequency drives, power-management systems, programmable controllers, and industrial software. | Electric submersible pumps, compressor stations, drilling support systems, terminals, and refinery utilities. | Strong presence across North America, Europe, the Middle East, and fast-growing Asian energy markets. | IEC 60204 IEC 61850 Modbus TCP PROFINET | Electrification, energy optimization, remote operations, integrated power-and-process control, and emissions reduction. | Electrification-heavy projects and facilities requiring coordinated power, motor, and process control. |
| 3 | Safety and Critical Operations Specialist | Emergency shutdown systems, fire and gas systems, burner management, high-integrity pressure protection, and safety lifecycle tools. | Offshore platforms, FPSOs, LNG plants, gas processing, hazardous-area facilities, and high-pressure production systems. | Global reach with particularly strong activity in offshore, LNG, Middle Eastern, and European projects. | IEC 61508 IEC 61511 ISA 84 IEC 60079 | Digital safety lifecycle management, proof-test optimization, wireless sensing, and integrated fire-and-gas analytics. | Safety-critical brownfield upgrades and projects with stringent functional-safety requirements. |
| 4 | SCADA and Pipeline Automation Provider | SCADA platforms, remote terminal units, telemetry, pipeline leak detection, flow computers, and control-room software. | Crude-oil pipelines, gas transmission, gathering networks, compressor stations, storage, and distribution infrastructure. | North America, Europe, Central Asia, the Middle East, and long-distance pipeline corridors worldwide. | DNP3 IEC 60870-5-104 Modbus OPC UA | Edge computing, satellite connectivity, AI-assisted leak detection, digital pipeline twins, and remote asset diagnostics. | Geographically distributed assets with demanding communications, reliability, and control-room requirements. |
| 5 | Measurement and Instrumentation Specialist | Pressure, temperature, flow, level, analytical, metering, and wireless instrumentation for process industries. | Custody transfer, well pads, separation, tank farms, gas quality measurement, refining, and loading terminals. | Broad international coverage through regional engineering, service, and distribution networks. | HART FOUNDATION Fieldbus IEC 61508 API MPMS | WirelessHART, smart metering, in-line analysis, remote calibration, and data-driven asset performance monitoring. | Measurement-intensive projects where accuracy, traceability, and equipment reliability are priorities. |
| 6 | Industrial Software and Operations Management Provider | Manufacturing execution systems, historian platforms, asset-performance management, production optimization, and enterprise integration. | Refinery production management, maintenance planning, energy management, production allocation, and operations reporting. | Global software deployment capability across mature and emerging oil and gas markets. | ISA-95 OPC UA MQTT ISO 55001 | Industrial artificial intelligence, cloud analytics, digital twins, generative assistance, and connected worker applications. | Multi-site digital transformation and integration of operational technology with enterprise systems. |
| 7 | Rotating Equipment and Condition Monitoring Provider | Vibration monitoring, machinery protection, compressor controls, turbomachinery control, predictive diagnostics, and performance monitoring. | Gas turbines, centrifugal compressors, pumps, LNG trains, refinery rotating equipment, and offshore production machinery. | Strong reach in regions with significant LNG, refining, offshore, and gas-transmission infrastructure. | API 670 API 618 ISO 20816 OPC UA | Machine-learning diagnostics, digital performance models, remote expert services, and maintenance optimization. | Reliability-centered maintenance and high-value rotating-equipment protection. |
| 8 | Valve, Actuation, and Final-Control Specialist | Control valves, on-off valves, electric and pneumatic actuators, positioners, valve diagnostics, and emergency isolation systems. | Wellheads, pipelines, process units, tank farms, gas plants, LNG facilities, and emergency shutdown applications. | Worldwide service coverage with extensive activity in upstream, midstream, refining, and LNG markets. | IEC 61508 API 6D IEC 60534 IEC 60079 | Smart valve diagnostics, partial-stroke testing, low-emission packing, remote condition monitoring, and electrified actuation. | Process reliability, flow control, emissions compliance, and safety isolation. |
| 9 | Industrial Cybersecurity and Secure Connectivity Provider | Industrial firewalls, secure remote access, network monitoring, asset discovery, intrusion detection, and security governance tools. | Control rooms, offshore installations, refineries, pipelines, terminals, substations, and distributed production networks. | Global demand driven by critical-infrastructure protection requirements and expanded remote operations. | IEC 62443 NIST CSF ISO 27001 NERC CIP | Zero-trust architecture, behavioral analytics, managed detection, secure-by-design engineering, and supply-chain risk monitoring. | Brownfield security upgrades and protection of converged IT and operational technology environments. |
| 10 | Robotics, Inspection, and Remote Operations Provider | Inspection robots, remotely operated vehicles, machine vision, autonomous drones, digital inspection systems, and remote-control platforms. | Offshore inspection, tank inspection, flare monitoring, pipeline surveys, confined spaces, and hazardous-area maintenance. | Growing global reach, especially in offshore, remote, hazardous, and labor-constrained operating environments. | ISO 10218 IEC 61508 IEC 60079 API 653 | Autonomous inspection, computer vision, remote intervention, robotic cleaning, and reduced-exposure maintenance. | Asset integrity, worker-safety improvement, and inspection of difficult or hazardous locations. |
Note: The ranking represents commonly observed supplier capability categories and worldwide market relevance rather than a company-specific revenue or market-share ranking. Regional reach and technology adoption can vary by project, regulatory environment, and local system integrator.