China Top 10 Automation Industry Suppliers?

China’s automation industry has moved far beyond basic assembly lines. Today, Chinese suppliers build PLC systems, servo drives, machine-vision equipment, industrial robots, and warehouse solutions. Some focus on precision motion control. Others offer complete production cells with software, sensors, and after-sales support.

This guide examines China’s top 10 automation industry suppliers through practical criteria. These include product reliability, engineering capability, certifications, export experience, integration skills, and service coverage. A factory audit can reveal more than a polished catalog. Response time matters. Spare parts matter even more.

Bill Gates wrote in Business @ the Speed of Thought, “The first rule of any technology used in a business is that automation applied to an efficient operation will magnify the efficiency.” That principle remains highly relevant. Automation does not repair every weak process. It can sometimes make waste faster and more expensive.

The companies discussed here serve different industries, including automotive, electronics, packaging, logistics, and energy. Their strengths are not identical. One supplier may provide excellent robots but limited software support. Another may offer strong customization but slower delivery. No ranking is perfect. Buyer requirements change by factory size, production volume, budget, and technical risk. This overview therefore aims to provide a realistic starting point, not a final purchasing decision.
China Top 10 Automation Industry Suppliers?

China’s Automation Industry: Scope, History, and Market Structure

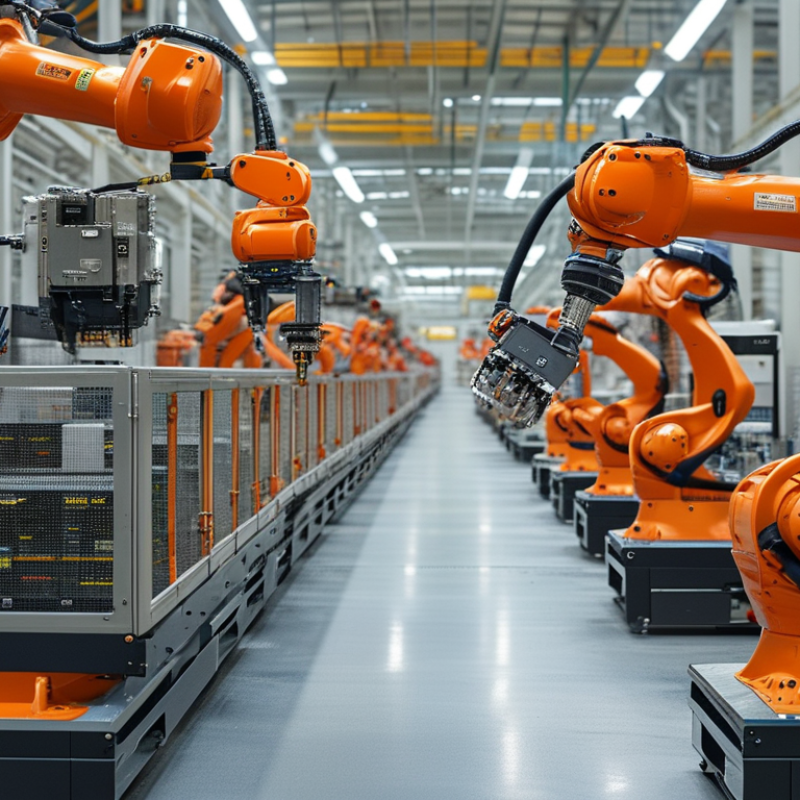
China’s automation industry spans industrial robots, control systems, sensors, machine vision, drives, software, and factory integration. It serves electronics, automobiles, logistics, food processing, and battery manufacturing. The sector began building research capacity in the 1980s, then accelerated during the 2010s as labor costs rose and smart-factory policies expanded. Today, factories often combine robotic arms, conveyor systems, barcode readers, and production software around one workstation.

The scale is substantial. The International Federation of Robotics reported 276,288 industrial robot installations in China during 2023, representing 51% of global installations. Its operational robot stock exceeded 1.7 million units. China’s robot density reached about 470 units per 10,000 manufacturing employees, according to World Robotics 2024. These figures show strong adoption, but they do not prove equal automation quality. A fast robotic arm still depends on stable power, accurate calibration, trained technicians, and reliable data links.

Market structure remains layered. Equipment manufacturers supply core hardware, systems integrators connect production cells, and software providers manage scheduling, quality, and maintenance data. Public policy supports domestic capability, while international supply chains still influence advanced components and engineering practices. The Ministry of Industry and Information Technology has emphasized intelligent manufacturing and industrial software in recent development plans. Yet smaller factories often face high integration costs and weak internal skills. That gap is easy to underestimate. A machine may run smoothly during installation, then lose efficiency when operators cannot adjust sensors or diagnose faults.
How China’s Top 10 Automation Suppliers Are Selected

China Top 10 Automation Industry Suppliers?

How China’s Top 10 Automation Suppliers Are Selected

A credible top-ten list needs more than shipment numbers or online visibility. We assess suppliers through technical capability, delivery performance, service quality, and documented customer experience. The review covers industrial robots, motion control, machine vision, control systems, and factory integration.

Evidence matters. We examine product specifications, certification records, testing procedures, and maintenance documentation. Factory visits can reveal practical details, such as cabinet wiring, spare-parts storage, and quality checks before shipment. We also contact users when possible. Their feedback may expose delayed responses or difficult software updates.

Supplier interviews are useful, but they are not enough. We compare claims with project records and installation results. A strong supplier should explain cycle time, accuracy, operating limits, and training requirements clearly. It should also provide dependable support after commissioning. Response time matters when a production line stops.

No ranking is perfect. Some smaller suppliers have excellent engineers but limited overseas service capacity. Some large suppliers provide broad solutions but slower customization. These differences require careful weighting. We consider long-term reliability, not only low pricing or impressive demonstrations. The final selection reflects available evidence, current market conditions, and reasonable professional judgment.

Profiles of China’s Top 10 Automation Industry Suppliers

China’s automation sector includes suppliers with different strengths, factory scales, and engineering histories. This profile guide examines ten representative supplier types.

A Shenzhen motion-control supplier develops servo drives for packaging lines and CNC equipment. Its engineers often test heat, vibration, and cycle accuracy before shipment. A Suzhou PLC specialist focuses on stable control systems, remote diagnostics, and practical programming support. A Dongguan robotics supplier builds six-axis robots for welding, assembly, and material handling. Factory trials matter here. A Guangzhou machine-vision supplier combines cameras, lighting, and inspection software for small electronic parts. Its results depend heavily on lighting design, not only algorithms. A Ningbo sensor manufacturer produces proximity, pressure, and photoelectric devices for demanding production areas.

A Wuxi variable-frequency-drive supplier serves pumps, conveyors, and compressors. Energy data and fault records help customers adjust operating costs. A Shanghai industrial-software supplier connects production data with traceability and maintenance planning. Integration can be difficult. A Foshan packaging-automation supplier designs filling, labeling, and carton-sealing equipment for food and consumer goods. Clean layouts and accessible replacement parts are important. A Tianjin warehouse-automation supplier provides conveyors, sorting systems, and storage controls. Its performance depends on accurate site measurements. A Chongqing system integrator combines robots, sensors, safety controls, and operator training for complete production cells.

Reliable evaluation should include certifications, test records, local service coverage, spare-parts availability, and verified customer references. Price alone can hide integration costs. Some suppliers communicate technical details well but underestimate commissioning time. Buyers should request factory demonstrations, written performance limits, and clear warranty terms before signing contracts.

China’s Automation Industry: Key Market Indicators

China remains the world’s largest industrial robot market. The chart presents publicly reported, industry-level indicators rather than company or brand data, highlighting the scale of automation adoption and manufacturing demand.

Core Technologies and Industries Served by Leading Suppliers

Leading automation suppliers in China compete through core technologies, not catalog size alone. Their portfolios typically include programmable controllers, servo drives, motion-control systems, machine vision, industrial robots, and factory software. Strong suppliers connect these layers through industrial Ethernet and real-time data platforms. This reduces wiring, improves traceability, and supports faster production changes. In practical audits, integration quality often matters more than a single component’s specifications. That detail is easy to overlook.

The International Federation of Robotics reported 276,288 industrial robot installations in China during 2023, representing 51% of global installations. Its World Robotics 2024 report also recorded about 470 robots per 10,000 manufacturing employees in China. These figures explain the demand for reliable programming, predictive maintenance, and secure data exchange. Leading suppliers serve automotive assembly, electric-vehicle batteries, electronics, metal processing, logistics, food production, and pharmaceuticals. Machine vision checks tiny solder joints, while collaborative systems support repetitive handling near workers. Digital twins help engineers test cycle times before equipment reaches the floor. However, digital transformation is not automatically successful. Poor sensor calibration, weak training, and incompatible protocols can erase expected gains. The best evaluation should therefore examine uptime records, service response, cybersecurity practices, and compatibility with existing equipment. Capability varies by industry.

Market Trends and Future Outlook for China’s Automation Sector

China’s automation sector is moving from rapid equipment adoption toward deeper factory integration. The International Federation of Robotics reported 276,288 industrial robot installations in China during 2023, representing about 51% of global installations. Its operational robot stock exceeded 1.75 million units. These figures show strong demand, but they do not prove that every factory is becoming efficient.

The supplier landscape is also changing. A top-ten ranking now depends on more than robot sales. Buyers increasingly assess machine vision, motion control, industrial software, system integration, maintenance, and cybersecurity. The Ministry of Industry and Information Technology has identified intelligent manufacturing as a strategic development area in its 14th Five-Year Plan. Investment is especially visible in electric vehicles, batteries, electronics, logistics, and precision machinery. Smaller factories remain cautious because integration costs, worker training, and uncertain payback can weaken adoption.

The outlook is promising, yet uneven. IFR data placed China’s manufacturing robot density at 470 units per 10,000 employees in 2023, showing progress but also room for expansion. Future growth may come from flexible systems that can change tasks quickly, rather than fixed production lines alone. Artificial intelligence will improve inspection and scheduling, but reliable deployment still requires clean data and skilled technicians. That gap is easy to underestimate. Supplier rankings may therefore shift as customers demand measurable uptime, safer collaboration, open interfaces, and long-term service. The market’s next challenge is not buying more machines. It is making them work together.

China Top 10 Automation Industry Suppliers? - Market Trends and Future Outlook for China’s Automation Sector

Evidence-Based Supplier Segments and Market Outlook
Rank Supplier Segment Core Automation Products Main Application Sectors Market Relevance 2024–2028 Outlook Key Growth Drivers Competitive Challenge
1 Industrial Robot Suppliers Articulated robots, SCARA robots, collaborative robots and robotic cells Automotive, electronics, metal processing, logistics and general manufacturing Very High High Growth Labor-cost pressure, flexible production, reshoring of supply chains and smart-factory investment Price competition, software capability and integration quality
2 Motion-Control and Servo Suppliers Servo motors, servo drives, motion controllers and precision actuators Machine tools, packaging, semiconductors, batteries and textile machinery Very High High Growth Demand for higher speed, accuracy, energy efficiency and locally available components Precision performance, reliability and compatibility with control platforms
3 Programmable Logic Controller Suppliers PLCs, remote I/O, safety controllers and industrial communication modules Discrete manufacturing, process industries, utilities and infrastructure Very High Steady Growth Factory digitalization, equipment upgrades and demand for integrated control architectures Cybersecurity, ecosystem openness and engineering-service capability
4 Industrial Sensor and Machine-Vision Suppliers Photoelectric sensors, encoders, 3D vision systems and inspection cameras Electronics, pharmaceuticals, food processing, logistics and battery manufacturing High High Growth Quality traceability, defect reduction, inline inspection and artificial-intelligence adoption Lighting conditions, algorithm accuracy and integration with production software
5 Industrial Control and Drive Suppliers Variable-frequency drives, industrial PCs, control cabinets and automation software HVAC, water treatment, chemicals, metals, machinery and energy systems High Steady Growth Energy-saving requirements, process optimization and replacement of aging equipment Long qualification cycles and demanding industrial reliability standards
6 Warehouse and Logistics Automation Suppliers Automated storage and retrieval systems, conveyors, sorters and warehouse software E-commerce, express delivery, retail, cold chain and manufacturing logistics High High Growth Rapid order fulfillment, labor shortages, warehouse-density requirements and omnichannel retail High project cost, software interoperability and uneven customer utilization
7 Mobile Robot and Autonomous Logistics Suppliers AGVs, AMRs, autonomous forklifts and fleet-management platforms Factories, warehouses, hospitals, airports and commercial facilities High High Growth Flexible material handling, safer operations and lower dependence on fixed infrastructure Navigation reliability, safety certification and return-on-investment pressure
8 Process Automation and Instrumentation Suppliers Distributed control systems, process instruments, analyzers and safety systems Oil and gas, chemicals, power generation, water treatment and pharmaceuticals Medium-High Moderate Growth Safety compliance, emissions monitoring, process efficiency and infrastructure modernization Complex project execution, certification requirements and conservative procurement
9 Digital Manufacturing and Industrial Software Suppliers MES, SCADA, industrial IoT platforms, digital twins and predictive-maintenance software Automotive, electronics, machinery, energy and multi-site manufacturing High Very High Growth Data integration, production visibility, artificial intelligence and carbon-accounting needs Data silos, cybersecurity, implementation complexity and shortage of skilled personnel
10 System Integrators and Automation Engineering Providers Turnkey production lines, robotic workstations, retrofit services and engineering support Automotive, batteries, electronics, food, pharmaceuticals and general industry Very High Steady Growth Customer demand for complete solutions, localized service and faster deployment Dependence on engineering talent, project execution risk and limited scalability
Market Reference Indicators: China installed 276,288 industrial robots in 2023, representing approximately half of global installations, according to the International Federation of Robotics. China’s robot density reached about 470 robots per 10,000 manufacturing employees in 2023. The sector is being supported by industrial digitalization, equipment renewal, new-energy manufacturing, labor-efficiency requirements and the development of smart factories.
Note: The ranking reflects supplier-segment importance in China’s automation ecosystem rather than the revenue ranking of individual companies or brands. Market outlook categories are qualitative assessments based on published industrial-automation trends and sector demand indicators.